
Insurance Coverage Guide for Zepbound
Zepbound Cost With Insurance in 2026
Zepbound cost with insurance depends almost entirely on one question: does your plan cover anti-obesity medication at all? When a commercial plan covers it and the Zepbound savings card applies, eligible patients pay as little as $25 for a 1-month, 2-month, or 3-month fill of the single-dose pen. When the plan denies that same pen, the card drops to a $499 monthly price. Medicare beneficiaries got a third route on July 1, 2026: the CMS Medicare GLP-1 Bridge, which offers the Zepbound KwikPen at $50 a month through December 31, 2027.
Key Takeaways
- Coverage is the whole ballgame. With commercial coverage plus the savings card, eligible single-dose pen patients pay as low as $25 per fill. When the plan does not cover that pen, the card lands at $499 a month.
- Employer coverage is growing but not universal. KFF's 2025 employer survey found 43% of firms with 5,000 or more workers covered GLP-1s for weight loss, up from 28% in 2024. Among firms with 200 or more workers, 19% did.
- The with-coverage tier has an annual ceiling. On the with-coverage single-dose pen tier, Lilly caps total savings at $1,300 per calendar year. Mounjaro's separate card carries a $1,950 annual cap.
- Prior authorization is the normal path. Lilly's access materials list the documentation categories insurers ask for.
- Medicare has a temporary route. The Medicare GLP-1 Bridge runs July 1, 2026 through December 31, 2027 at $50 a month, and covers the Zepbound KwikPen only. The single-dose vial and single-dose pen are excluded.
- Paying cash instead? See our full breakdown of Zepbound cash-pay and LillyDirect vial pricing. This guide covers the insured path only.
$25
Single-Dose Pen, Covered
$1,300
Annual Cap, Covered Tier
$50
Medicare Bridge per Month
43%
Largest Employers Covering
Quick Answer: Zepbound Cost With Insurance by Plan Type
Six pathways account for nearly everyone filling a Zepbound prescription in the United States. The figures below are the out-of-pocket price after the relevant program is applied, not the list price.

How this guide differs from our Zepbound cost guide
Two separate questions get asked with the same words. This page answers the insured one: how coverage decisions, prior authorization, formulary placement, and government programs determine what you hand over at the pharmacy counter. If you are paying entirely out of pocket, the cash-pay ladder is a different set of numbers and lives in our full breakdown of Zepbound cash-pay and LillyDirect vial pricing, with enrollment mechanics in the LillyDirect Zepbound guide.
Model Your Annual Zepbound Spend
Lilly's posted terms state the card expires and savings end on 12/31/2026, and the with-coverage tier carries its own annual ceiling. Use the tirzepatide calculator to map your titration schedule against fill dates so you can see how many fills the year actually holds.
Open Tirzepatide Calculator →Does Insurance Cover Zepbound for Weight Loss?
Coverage for anti-obesity medication is a benefit design choice made by your employer or plan sponsor, not a property of Zepbound itself. That is why two people with the same carrier can get opposite answers. The 2025 KFF Employer Health Benefits Survey, analyzed by the Peterson-KFF Health System Tracker, found 19% of firms with 200 or more workers covered GLP-1 agonists for weight loss. Among firms with 5,000 or more workers, 43% did, up from 28% the previous year.
The increase sits with the largest firms. KFF reports no comparable trend for smaller ones, and the same survey found many employers considering scaling coverage back. Neither figure is a probability for your specific plan, and no published source breaks coverage down carrier by carrier, so the only reliable move is to call the pharmacy benefits number on the back of your card and ask two questions: is Zepbound on the formulary, and what tier is it on.
The two indications matter
Zepbound carries an FDA approval for chronic weight management and a second approval for moderate-to-severe obstructive sleep apnea in adults with obesity, granted in December 2024. Some plans that exclude weight-management drugs as a class will still cover Zepbound when it is prescribed for sleep apnea. If you have a documented OSA diagnosis, that is worth raising with your prescriber before assuming a denial is final.
For the molecule-level view across both Lilly tirzepatide brands, including how Mounjaro's diabetes indication changes the coverage picture, see our tirzepatide cost guide and the Mounjaro cost breakdown.
The Zepbound Savings Card With Commercial Coverage
The savings card is a copay reducer, not insurance. It sits on top of a commercial plan that already pays part of the bill and absorbs some of what is left. This tier applies to the Zepbound single-dose pen when your plan covers it. Lilly's terms describe paying $25 for a 1-month, 2-month, or 3-month fill, and card savings are capped at up to $100 per 1-month, $200 per 2-month, or $300 per 3-month fill, with a separate maximum annual savings of $1,300 per calendar year across up to 13 fills. The $25 figure is a floor, not a guarantee: if your plan's cost share exceeds the per-fill maximum savings, you pay the difference.
That $1,300 ceiling belongs to the with-coverage single-dose pen tier specifically. The without-coverage tiers, which cover patients whose plans deny the drug, are priced differently and carry no stated annual cap. Mounjaro's separate savings program has its own $1,950 annual cap. Two brands, several tiers, so don't carry an assumption from one to the other. Lilly's posted terms also state the card expires and savings end on 12/31/2026, with no published reset beyond that date.
Government plans are excluded
Manufacturer copay cards cannot be used by patients enrolled in Medicare, Medicaid, TRICARE, the VA, or any other federal or state healthcare program. This constraint applies industry-wide, not just to Lilly, and it holds regardless of how much you would otherwise save.
The current eligibility check and full terms are posted at zepbound.lilly.com/savings, listed in the references below. Our Zepbound savings card guide walks through activation and the without-coverage tiers in more detail.
Prior Authorization: What Insurers Require and How It Works
Lilly states that most Zepbound prescriptions for the single-dose pen will require a prior authorization form. Your prescriber submits clinical documentation, the plan or its pharmacy benefit manager reviews it against internal criteria, and coverage turns on or stays off based on that review. Lilly's access and coverage materials group the information insurers typically request into five categories:
- Current weight and BMI, usually measured in the clinic rather than self-reported
- How long you have struggled with weight, establishing that this is a chronic condition
- Diet and exercise history, including structured programs you have completed
- Prior weight-management medications you have tried and what happened
- Weight-related comorbidities such as hypertension, dyslipidemia, type 2 diabetes, or obstructive sleep apnea
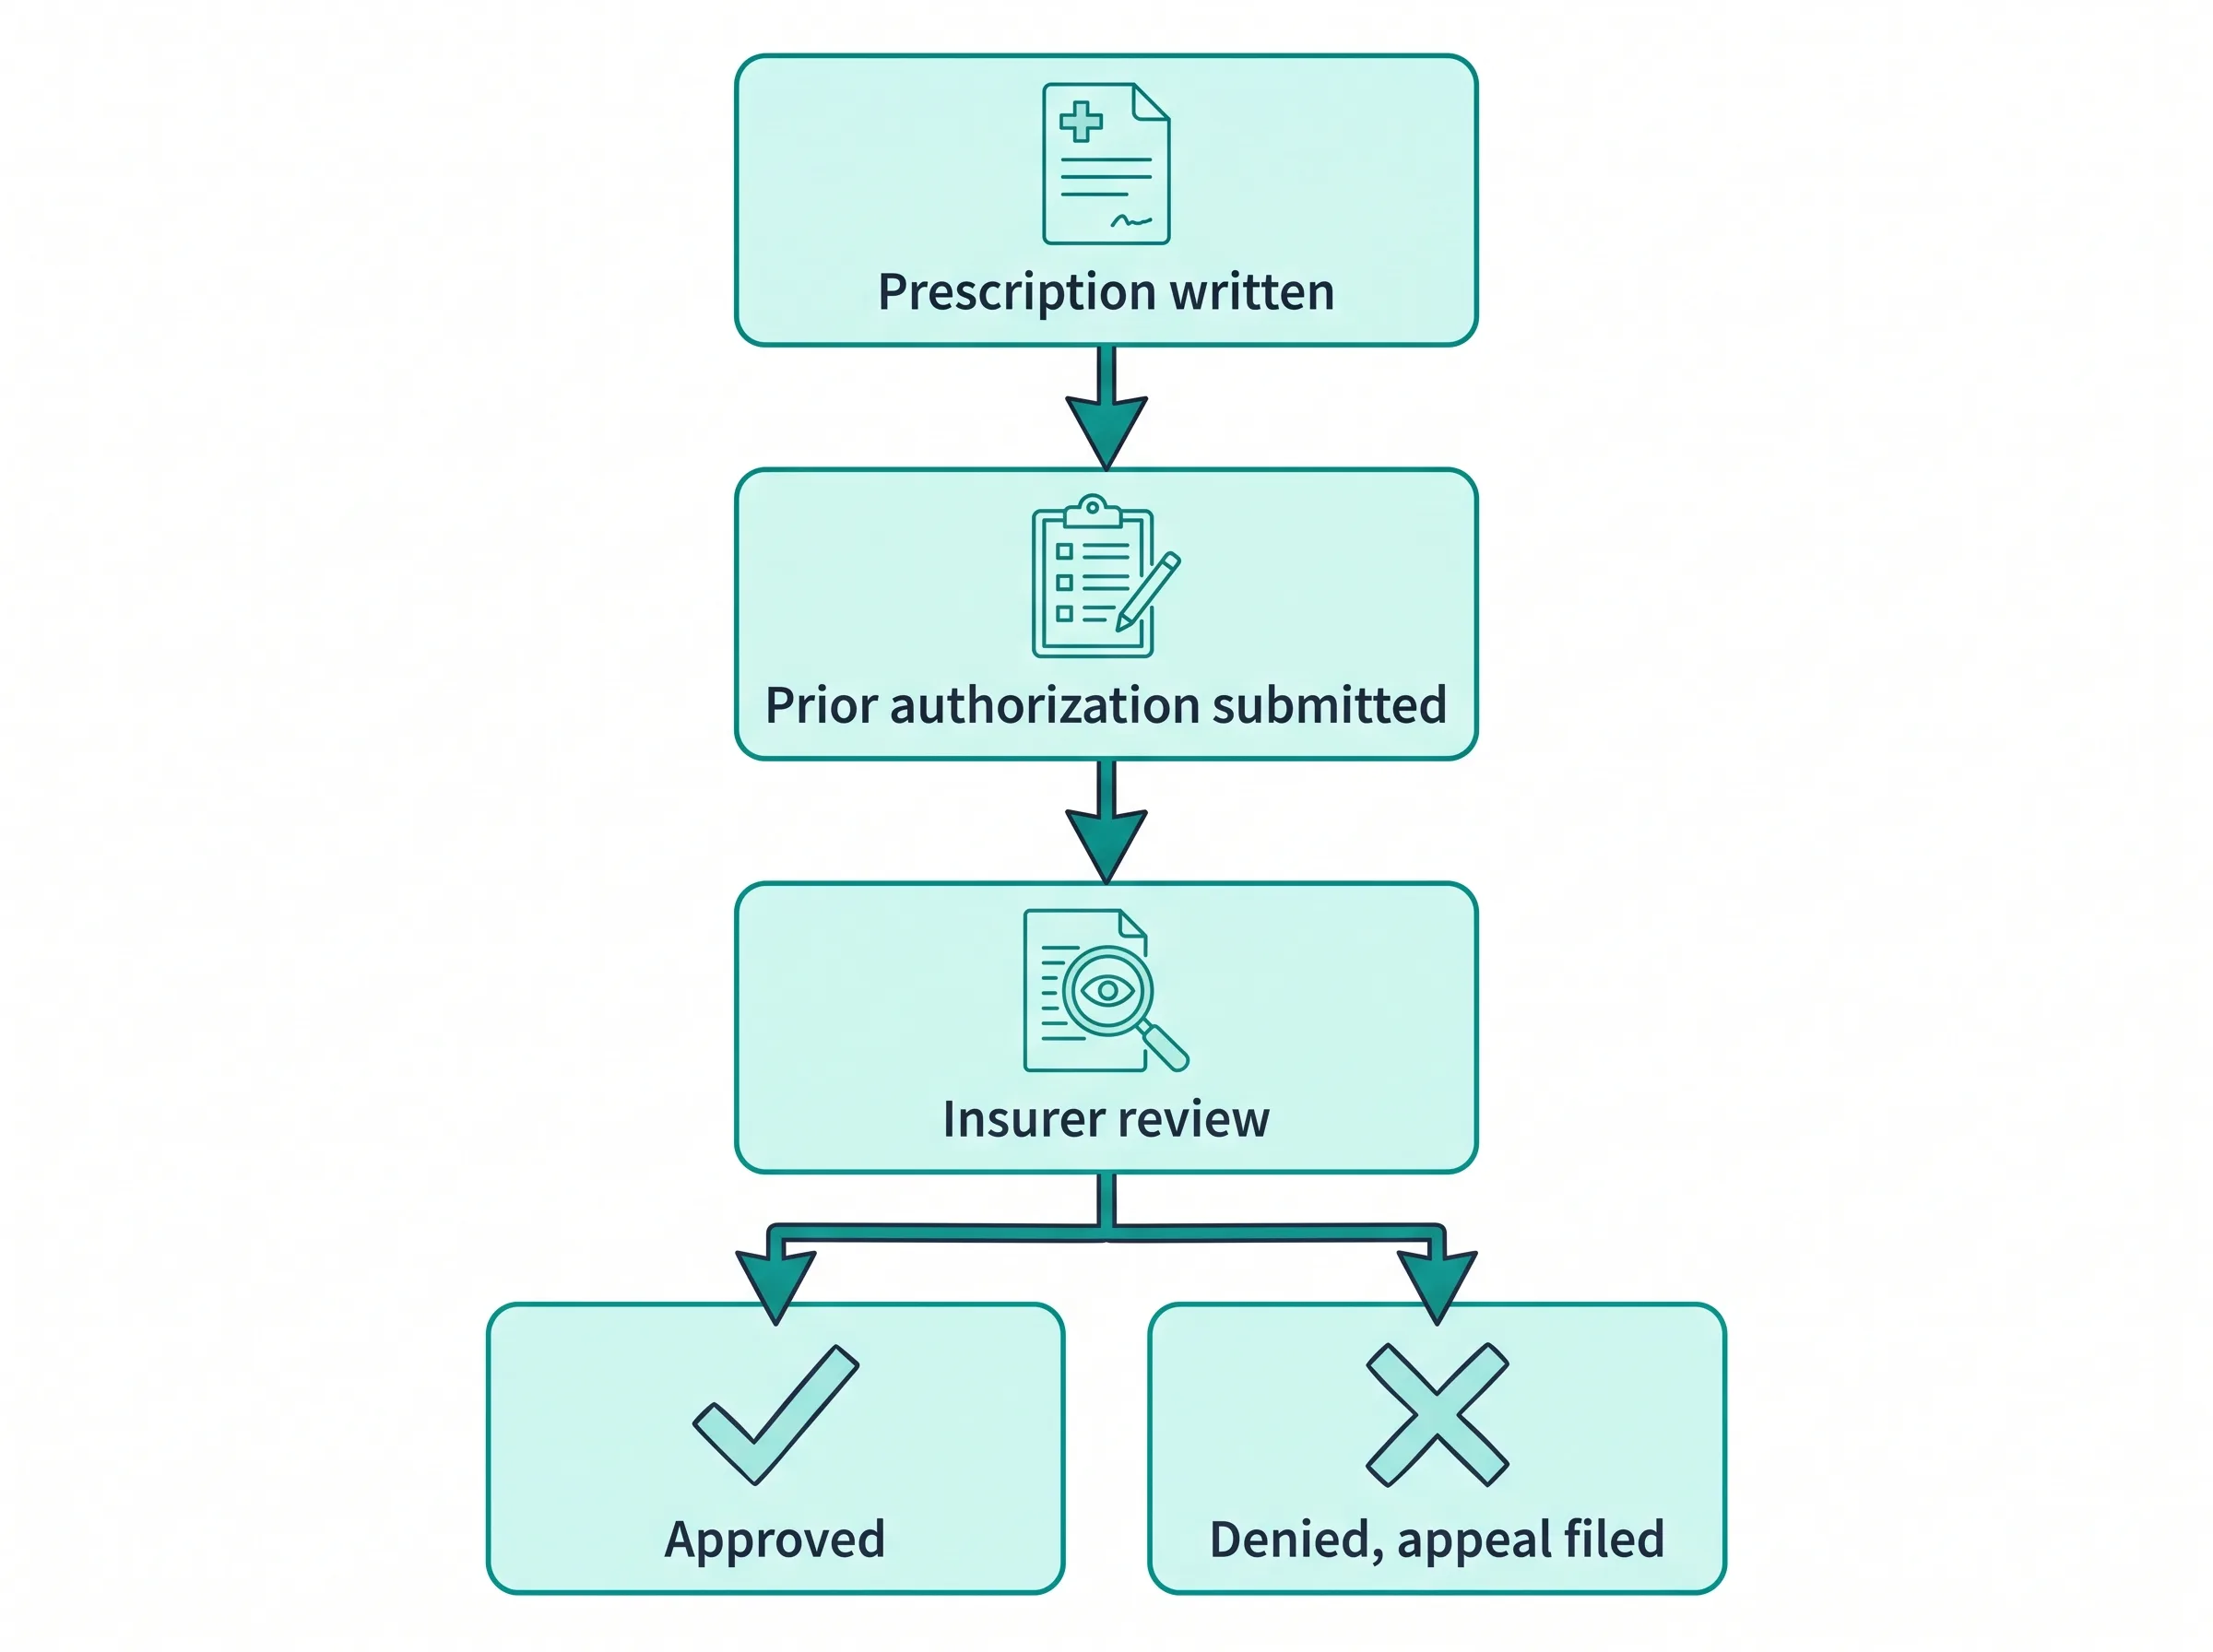
Gathering that documentation before the appointment tends to shorten the process. Old weigh-ins, weight-loss program records, and notes from a prior medication trial all count as evidence, and reconstructing them after a denial takes longer.
The video below explains how prior authorization works across prescription drugs generally: why plans use it, how pharmacy benefit managers apply criteria, and what step therapy means. It is not Zepbound-specific.
Video: Prescription Medication Prior Authorization Explained
AHealthcareZ, a physician-run healthcare finance education channel, explains the prior authorization mechanism (18:17).
If your prior authorization is denied
A denial is a step, not the end. Lilly's access and coverage guidance states that if your prior authorization is denied, your healthcare provider can submit an appeal. The appeal usually pairs the clinical documentation with a letter of medical necessity from your prescriber.
Ask your plan for the denial reason in writing before appealing. A missing lab value, an unmet step-therapy requirement, and a categorical benefit exclusion all read as "denied" but call for different responses. A categorical exclusion, where the plan does not cover anti-obesity medication at all, generally will not be overturned on clinical grounds, and your energy is better spent on the routes further down this page.
A Note on Copay Accumulator Programs
Some employer plans run copay accumulator or copay maximizer programs. Manufacturer copay-card assistance still pays down your bill at the pharmacy, but the plan does not credit that assistance toward your deductible or out-of-pocket maximum.
The effect is easy to miss. Card savings top out at $100 on a 1-month fill, so the assistance is modest to begin with, and none of it moves your deductible.
No source we consider reliable states how many plans apply these programs to Zepbound specifically, so we are not going to put a percentage on it. Ask your benefits administrator whether manufacturer assistance counts toward your deductible. It's a yes-or-no question, and the answer changes how you budget.
Zepbound Cost With Insurance Under Medicare: The New GLP-1 Bridge
This is the part of the picture that changed most recently, and older coverage guides do not reflect it. CMS announced on May 6, 2026 that it would provide eligible Medicare beneficiaries access to certain GLP-1 medications for $50 per month beginning July 1, 2026, through December 31, 2027. That program is the Medicare GLP-1 Bridge.
KwikPen only, and the distinction is not cosmetic
Per the CMS guidance for Part D plans, the KwikPen formulation of Zepbound is the formulation available through the Medicare GLP-1 Bridge. The single-dose vial and single-dose pen formulations of Zepbound are not available through the Bridge. The mirror image matters here. The Bridge covers the KwikPen only, while Lilly's commercial $25 savings tier covers the single-dose pen only. Opposite devices, opposite programs, so the formulation written on the prescription decides which discount you can reach at all.
Clinical eligibility, as CMS defines it
The criteria are conjunctive, not a menu. The prior authorization must attest that the drug is prescribed to reduce excess body weight in combination with current and ongoing lifestyle modification including structured nutrition and physical activity, and that the beneficiary, aged 18 or older, meets one of these BMI tiers. CMS measures BMI at the time of initiation of GLP-1 therapy.
- BMI of 35 or higher with no additional diagnosis required
- BMI of 30 or higher with heart failure with preserved ejection fraction, uncontrolled hypertension, or chronic kidney disease stage 3a or above
- BMI of 27 or higher with pre-diabetes, a previous myocardial infarction, a previous stroke, or symptomatic peripheral artery disease. If the drug is being prescribed to reduce the risk of major adverse cardiovascular events, whether or not it is also prescribed to reduce excess weight, CMS says that prescription should be routed to the Part D plan instead.
The prior-GLP-1 disqualifier catches a lot of people
CMS excludes any beneficiary who already received a GLP-1 drug through Part D in calendar year 2026. The lookback list includes Zepbound, Mounjaro, Foundayo, Rybelsus, Ozempic, Wegovy, Saxenda, Victoza, and Trulicity. If you filled any of those under Part D this year, the Bridge is closed to you, so check your Part D claims history before building a plan around the $50 price.
Three mechanics worth knowing before you enroll
- You cannot stack a manufacturer coupon on it. CMS states the Bridge is the primary payer for covered products, does not coordinate benefits with other payers, and that coupons and discount programs may not be applied to Bridge claims.
- Humana processes the claims. CMS is using Humana, administrator of the Limited Income Newly Eligible Transition program, as the central processor.
- The end date is real. The program runs through December 31, 2027. Treat the $50 price as a defined window, not a permanent Medicare benefit.
If you do not qualify for the Bridge
Outside the Bridge, Medicare Part D excludes drugs used for weight loss under a longstanding statutory provision, section 1860D-2(e)(2)(A) of the Social Security Act. That exclusion is the reason Medicare beneficiaries have historically had no Part D route to Zepbound for obesity alone.
There is an important carve-out running the other direction, and it cuts harder than it first reads. CMS states that the type 2 diabetes, moderate-to-severe obstructive sleep apnea, and MASH with moderate-to-advanced fibrosis indications are eligible for ordinary Part D coverage, and that beneficiaries with those diagnoses are not eligible for coverage under the Medicare GLP-1 Bridge regardless of whether their current Part D plan covers a GLP-1 drug for that condition. Zepbound holds an FDA approval for moderate-to-severe obstructive sleep apnea, so that diagnosis takes you out of the Bridge whether or not your plan actually pays. CMS does not promise a working route, only that the Bridge is not it. Confirm your plan's formulary status rather than assuming the Part D door is open.
Medicaid and TRICARE Coverage for Zepbound
Neither permits the manufacturer savings card, but the coverage rules differ. TRICARE's pharmacy benefit covers weight-loss medications including Zepbound for TRICARE Prime and TRICARE Select beneficiaries with an approved prior authorization. Since August 31, 2025, that coverage no longer extends to beneficiaries outside Prime and Select, including TRICARE For Life. Medicaid is administered state by state, and anti-obesity drug coverage is an optional benefit each state program decides independently. That variation shifts as states revise formularies, and no source we would rely on keeps a current state-by-state table, so we will not publish a guessed one.
The workable step is the same in both cases: ask your state Medicaid program or TRICARE benefits office whether Zepbound is on the formulary for your indication, and whether a documented sleep apnea diagnosis changes the answer. Ask about the indication rather than the drug in the abstract, because that is the distinction the formulary is built on.
If Insurance Will Not Cover Zepbound at All
When the exclusion is categorical and an appeal is not going to move it, the question stops being an insurance question. The cash-pay routes are genuinely cheaper than the $1,086.37 list price, and they are a separate set of numbers with their own eligibility rules.
Start with our full breakdown of Zepbound cash-pay and LillyDirect vial pricing for the current price ladder by dose, and the LillyDirect Zepbound guide for enrollment and refill timing. One rule carries across both: cash-pay programs and insurance benefits are not designed to be combined, so pick one lane.
If you are weighing brand and indication questions first, our page on tirzepatide's FDA approval status covers which indications are approved for which brand, which is what formulary decisions turn on.
Frequently Asked Questions
Does insurance cover Zepbound for weight loss?
Coverage varies by employer and plan. KFF's 2025 employer survey found 43% of firms with 5,000 or more workers covered GLP-1s for weight loss, up from 28% in 2024, while 19% of firms with 200 or more workers did. Most plans that cover it require prior authorization documenting BMI and weight-related health history.
How do I get my insurance to approve Zepbound?
Your prescriber submits a prior authorization documenting current weight and BMI, how long you have struggled with weight, diet and exercise history, prior weight-management medications, and weight-related comorbidities. If it is denied, Lilly's access guidance states your healthcare provider can submit an appeal, typically with a letter of medical necessity.
What is the Zepbound savings card worth if my insurance covers it?
When your plan covers the Zepbound single-dose pen, eligible commercially insured patients can pay as low as $25 for a 1-month, 2-month, or 3-month fill. Card savings are capped at up to $100, $200, or $300 per fill by fill length, with a maximum annual savings of $1,300 per calendar year on that tier. Mounjaro's separate program caps at $1,950 per calendar year.
Does Medicare cover Zepbound?
Not under standard Part D for weight loss alone, which is statutorily excluded. From July 1, 2026 through December 31, 2027, the Medicare GLP-1 Bridge gives eligible Part D beneficiaries the Zepbound KwikPen for $50 a month. The single-dose vial and single-dose pen are not available through the Bridge.
Can I use the Zepbound savings card with the Medicare GLP-1 Bridge?
No. CMS states the Bridge is the primary payer for products it covers and does not coordinate benefits with other payers, and that coupons and discount programs may not be applied to Bridge claims. Manufacturer copay cards are separately unavailable to anyone enrolled in a federal healthcare program.
What BMI do I need to qualify for the Medicare GLP-1 Bridge?
Every tier also requires attestation that the drug is prescribed to reduce excess body weight alongside ongoing structured nutrition and physical activity, and anyone who already received a Part D GLP-1 in 2026 is excluded. A BMI of 35 or higher qualifies on its own. A BMI of 30 or higher qualifies alongside heart failure with preserved ejection fraction, uncontrolled hypertension, or chronic kidney disease stage 3a or above. A BMI of 27 or higher qualifies alongside pre-diabetes, previous myocardial infarction, previous stroke, or symptomatic peripheral artery disease.
I have sleep apnea and Medicare. Do I use the Bridge?
Not if the apnea is moderate-to-severe. CMS states that beneficiaries with type 2 diabetes, moderate-to-severe obstructive sleep apnea, or MASH with moderate-to-advanced fibrosis are not eligible for the Bridge regardless of whether their Part D plan covers a GLP-1 for that condition. Zepbound's FDA approval is for moderate-to-severe obstructive sleep apnea, so confirm your plan's formulary status rather than assuming either route is open.
Does Medicaid cover Zepbound?
Generally not for weight-loss-only use. Medicaid drug coverage for anti-obesity medication is decided state by state and changes as states revise formularies, so check with your specific state program. Manufacturer savings cards cannot be used with Medicaid regardless of the formulary answer.
Is prior authorization required for every Zepbound refill?
Not usually for each fill, but authorizations expire and need renewal, often tied to documented ongoing progress. Each plan sets its own renewal cadence, so ask your insurer for their reauthorization interval and documentation requirements rather than assuming a standard timeline.
What if my insurance denies Zepbound and I cannot afford the retail price?
You have routes beyond the $1,086.37 list price. See our full breakdown of Zepbound cash-pay and LillyDirect vial pricing for the current ladder of alternatives, including who qualifies and how the direct-to-consumer pharmacy partners work.
Plan Your Zepbound Year Around the Coverage You Have
- Confirm formulary status and tier first. Everything downstream depends on that one answer.
- Assemble prior authorization documentation before the appointment, not after a denial.
- On the with-coverage single-dose pen tier, watch the $1,300 annual savings ceiling, and ask whether card assistance counts toward your deductible.
- On Medicare, check the formulation. The Bridge covers the KwikPen, and it runs only through December 31, 2027.
References
- Centers for Medicare & Medicaid Services. Coming Soon: CMS to Provide $50 Monthly Access to GLP-1 Medications for Medicare Beneficiaries. CMS Press Release. May 6, 2026. cms.gov
- Centers for Medicare & Medicaid Services. Medicare GLP-1 Bridge: Information for Part D Plans. Accessed 2026-08-04. cms.gov Medicare GLP-1 Bridge
- U.S. Food and Drug Administration. ZEPBOUND (tirzepatide) injection, Full Prescribing Information. NDA 217806. 2025. accessdata.fda.gov
- U.S. Food and Drug Administration. FDA Approves First Medication for Obstructive Sleep Apnea. FDA Press Announcement. December 20, 2024. fda.gov
- Eli Lilly and Company. Zepbound Savings Card: Eligibility and Terms and Conditions. Accessed 2026-08-04. zepbound.lilly.com/savings
- Eli Lilly and Company. Zepbound Access and Coverage. Accessed 2026-08-04. zepbound.lilly.com/access-coverage
- Eli Lilly and Company. Zepbound Coverage, Affordability, and Savings (HCP). Accessed 2026-08-04. zepbound.lilly.com/hcp/coverage-savings
- Express Scripts. Are Glucagon-Like Peptide 1 (GLP-1) and weight loss medications covered through the TRICARE pharmacy benefit? Accessed 2026-08-04. militaryrx.express-scripts.com
- Peterson-KFF Health System Tracker. Perspectives from Employers on the Costs and Issues Associated with Covering GLP-1 Agonists for Weight Loss. 2025 KFF Employer Health Benefits Survey. Accessed 2026-08-04. healthsystemtracker.org
Medical Disclaimer: This article is for informational purposes only and does not constitute medical, insurance, or financial advice. Zepbound (tirzepatide) is an FDA-approved prescription medication. Coverage rules, program terms, and prices reflect publicly posted information as of August 2026 and are subject to change. Confirm current eligibility and pricing with your insurer, CMS, your pharmacy, and Eli Lilly before making decisions. Consult a qualified physician before starting, stopping, or changing any medication.
Related Reading
Zepbound Cost Without Insurance
The cash-pay side: list price and the LillyDirect vial ladder
Zepbound Savings Card Guide
Activation, the savings tiers, and how the annual cap works
Tirzepatide Cost Guide
Molecule-level view covering both Mounjaro and Zepbound pricing and coverage
Mounjaro Savings Card Guide
The separate Lilly program for the diabetes brand, with its own $1,950 annual cap